Showing posts with label Personal Finance Challenge. Show all posts

Saturday, January 1


here

It is officially 2011 and to celebrate I am kicking off the new year with a little challenge (resolutions are so 2010). I've decided to ban shopping (for clothes) until my last credit card is 100% paid off. [dun dun dun]. I know, I know, swearing off shopping is not exactly novel, but it is much needed. Lately, I've been taking the easy way out when it comes to my clothes. I wear the "same old, same old" for awhile and when I get bored I buy something shiny and new.

My estimated pay off date is March 30th which leaves me 90 days of no shopping, by far my longest self-imposed ban. I'll even open my pain up to all of you. Will you join me? Please? There is just one rule, there are no rules. Oh no wait, that's fight club. The one rule is, no shopping until my credit card's paid off. Deal? Deal.

Maybe I'll even get it paid off sooner to put us all out of our misery, me out of my debt, and SSF out of his constant state of worrying about money.

Hooray 2011!

What are your plans for the New Year? Will any of you actually play along with me? Does this cartoon make you laugh a little?


here

Wednesday, September 15

Snowflaking Update

For those of you that don't remember or are new to the blog each month I attempt a new personal finance "method" in an effort to pay off my debt, add to my savings, or just control my spending, whatever strikes my fancy. This month I am giving a go at "Snowflaking". A derivative of the debt snowball, snowflaking is taking the small sums of money that are left over from your budget at the end of the month and applying them to debt.

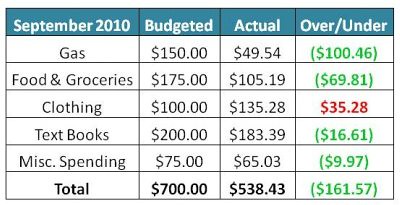
Here is where I stand as of end of day Tuesday (pardon the crappy graphic):

snowflaking 9.15

Some thoughts:

1. Eek! Over on clothing already?! I'm not surprised. After taking a free group personal training class this summer I decided to join the gym at work (so I could take it again, for free). I kind of went a little crazy buying some new items to prepare for impending fall temperatures (it's outside). A majority of this budget was spent at Under Armour, I love employee discounts.

2. I've had a lot of miscellaneous spending this month. One third of the budget went to buying a books both for me and SSBF so I could get a could start on my birthday goal of reading 6 books this year. I realize that we could have just gone to the library but I just love cracking open a brand new book to read.

3. I came under on textbooks! Thank you jesus. However I am still peeved that $60 went towards a freaking financial calculator that I will never use again!

4. Gas is on track to be $30 under for the month. I typically fill my tank every 7-10 days, at $35 a fill, even if I have to have to fill up twice before October that is $120.

5. Food has turned into "food and utilities".  Typically I give SSBF $90 towards groceries each month however we received our quarterly water and sewage bill this week which was fr $85 (normally $60) so I am paying that instead of paying for groceries. Anyway even with that I can see $15-$20 dollars under.

Overall I am feeling pretty good. At this point anything I can put towards my debt is helpful because the interest I am paying makes me cringe. It's sounds dorky, but keeping tracking of my spending this way has made me want to come in under budget, more then I ever have before. I think it's my competitive nature, I must win! I must beat this!

Sunday, August 29

Personal Finance Challenge: Snowflaking

Alright, so for those of you that have been with me for awhile you know that on Sunday's I normally do  "Spending Diary" from the previous week to keep me honest with my money. I realized though that each week was a lot of the same. I've done a pretty good job of reining in my casual spending so my day-to-day is well, boring. In an attempt to keep things interesting I've decided to make myself a personal finance guinea pig. Each month I'm am going to try a different personal finance method for debt repayment, saving, etc. Think of it as "Mythbusters" for personal finance.

Last month when I went to all cash was really my first crack at it minus the spiffy "Personal Finance Challenge" header. This month I'm taking a stab at "snowflaking".
Snowflaking can be used to both pay off debt and save money. The idea is taking small sums of money and contributing to your goal to help you reach it faster. My goal is to pay off the $6500 in credit card debt that has been haunting me since college so any "snowflakes" I have at the end of the month will be going towards the card.

Here is what I did:
First, I identified my variable expenses. These are ones that change every month. I have a lot of expenses, but most are fixed so I was able to narrow it down to only a few.

snowflaking budget

Next, I estimated how much I thought I would spend throughout the month of September. I based my estimates off of past spending for gas, food, clothes, and misc. For textbooks I took a wild stab in the dark and just assumed they would be ridiculously expensive... because they always are for business.

Now, I just do my thing and hope that I have some snowflakes to contribute to my credit card at the end of the month.

If you have any Personal Finance challenges for me, or would like to submit your own experience e-mail me at grace.croshaw@gmail.com

Sunday, August 22

Personal Finance Challenge: 30 Day Credit Card Ban (wrap-up)

I realized that because my vacation coincided with the finale of my credit card ban I never got a chance to sum up the month for you. So here it is:
What I Learned From a Month with No Credit:
1. I have more self-control than I ever give myself credit for. I started the month with $180 cash to spend on anything that wasn't a pre-budgeted bill or gas and ended with $15 still in my wallet.

2. Having a limited supply of money available for the month makes you question every purchase. Even when it came down to something as simple as lunch I found myself less willing to opt for a meal in the cafeteria.
Frivolous spending today only equated to less money tomorrow. 

3. On the other hand, when you truly love something you don't feel guilty handing over cash for it. Seriously, there was never any buyer's remorse here. I bought two items of clothing during my credit card ban, a dress from Goodwill and a scarf from Urban Outfitters and have not have any regrets.

4. Cash helps you look forward, instead of looking back. The thing about credits cards is that when the bill comes you are always paying for something from the past. Whether it be a meal, or clothing, or tickets to a baseball game it's already happened. It's almost impossible to plan for future expenses when you are trying to recall what was already spent. With cash, once the money leaves your hand it's paid for.

Finally,

5. Having cash on hand automatically makes you responsible for parking and tips.
Thanks SSBF.

Anyway, I would say if you are looking for a way to better control your cash flow I would recommend trying a credit detox for a month. It's actually quite liberating.

Next Month's Challenge: Snowflaking.
disclosure policy